How to Use PPO Dental Insurance to Save More in 2026
Learn how PPO dental insurance works, what it covers, and how to save money at Charming Smiles of Ocoee in 2026.
Key Takeaways
- PPO plans cover preventive care at 100% without deductible, but basic services cost 20-30% out-of-pocket and major services cost about 50%, so schedule preventive visits early to maximize benefits before annual maximums reset.
- Always call your dentist's office directly to confirm in-network status rather than relying on insurance websites, as networks change frequently and locations under the same name may have different coverage status.
- Request a predetermination or pre-treatment estimate from your dentist before major procedures like crowns or implants to get a strong cost estimate and avoid surprise bills after treatment.
- Annual maximums cap insurance company payments, not your personal spending; 73% of PPO enrollees now have at least $1,500 annual maximums, and 42% have rollover features that let unused benefits carry forward.
- Out-of-network dentists can balance bill you for the difference between their fee and your insurance's allowed amount, making in-network providers significantly more predictable and affordable.
- Check for waiting periods, frequency limits on cleanings, and missing-tooth clauses before starting treatment, especially if you're new to a plan, since these can create unexpected coverage gaps.
Getting a dental bill that's bigger than you expected is no fun for anyone. If you've ever squinted at an insurance statement wondering why your "covered" cleaning still cost you money, you're not alone. PPO dental insurance is the most common type of dental plan in the country, but it comes with rules that can feel confusing if nobody explains them clearly. That's exactly what we're doing here, in plain, friendly language.
At Charming Smiles of Ocoee, our team helps patients understand their benefits every single day. Whether you're a busy parent juggling checkups for the whole family, someone dreaming of a whiter smile, or a senior managing a few more dental needs, knowing how your PPO plan actually works can save you real money. Let's walk through it together, step by step, so you can walk into your next appointment feeling confident instead of confused.
What Is Dental PPO Insurance, Really?
PPO stands for Preferred Provider Organization. In simple terms, it's a type of dental plan that gives you choices. You can see almost any licensed dentist you want, but you'll usually pay less if you pick a dentist who is "in-network" with your plan.
Think of it like a discount club. In-network dentists have already agreed to set prices with your insurance company. This means your insurer knows exactly how much they'll pay, and you know roughly what you'll owe. Out-of-network dentists haven't agreed to those set prices, so your costs can be less predictable.
Here's some good news: PPO plans dominate the dental insurance world. According to the National Association of Dental Plans, PPO plans made up about 89% of all commercial dental plan enrollment in 2024. That means most people reading this probably already have one, even if they didn't know the name for it.
How PPO Plans Differ From DHMO Plans
You might have heard of DHMO plans too. Here's the biggest difference: DHMO plans usually require you to pick one primary dentist and get referrals to see a specialist. PPO plans are more relaxed. You typically don't need a referral, and you don't have to choose just one dentist. That flexibility is a big reason people love PPO coverage.
The Building Blocks of Your PPO Dental Plan
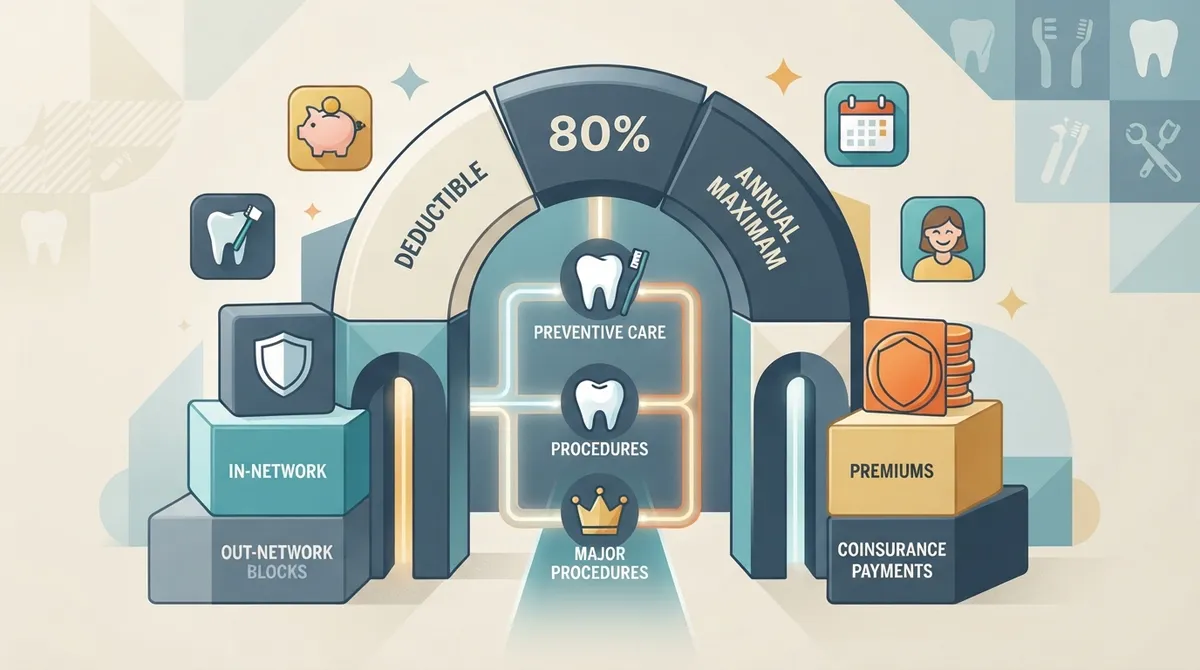
Every PPO plan is built from a few common pieces. Once you understand these terms, the rest of your insurance paperwork will make a lot more sense.
- Monthly premium: The amount you or your employer pays each month just to have the coverage.
- Annual deductible: The amount you pay out of pocket before insurance starts covering certain services.
- Coinsurance: The percentage split between what insurance pays and what you pay for a service.
- Annual maximum: The most your plan will pay in a single benefit year.
- Network allowance: The negotiated fee an in-network dentist agrees to accept for a service.
Preventive care, like your regular cleaning, often skips the deductible completely. Basic and major services usually come with more cost-sharing. This is why your six-month checkup might feel "free," but a filling or crown comes with a bill attached.
Understanding Your Annual Maximum
Your annual maximum is different from a medical insurance out-of-pocket maximum, and this trips a lot of people up. Once your plan pays out its annual maximum, you're responsible for the rest of your dental costs until the next benefit year starts. It doesn't cap how much you personally spend; it caps how much the insurance company spends.
The good news is that annual maximums have been improving. NADP reported that 73% of PPO enrollees had an annual maximum of at least $1,500 in 2025, up from 67% the year before. Some plans even offer a rollover feature, letting you carry over unused benefits to the next year. About 42% of PPO enrollees had this perk in recent data.
Sample PPO Plan Features You Might See
Every employer and insurer builds plans a little differently, but here's a general idea of what a typical dental PPO plan structure might look like based on recent industry data.
| Plan Feature | Common Range | What It Means for You |
|---|---|---|
| Annual Deductible | $50–$99 (most common) | Amount you pay before coverage kicks in for basic/major work |
| Annual Maximum | $1,500–$5,000 | Cap on what insurance will pay per year |
| Preventive Coverage | Often 100%, no deductible | Cleanings and exams usually cost little to nothing |
| Basic Services Coinsurance | 70%–80% typical | You may owe 20%–30% for fillings, extractions |
| Major Services Coinsurance | 50% typical | You may owe about half for crowns, bridges, dentures |
Remember, these numbers vary a lot by employer, insurer, and state. Your actual plan document, sometimes called a Summary of Benefits and Coverage, will have your exact numbers.
In-Network vs. Out-of-Network: What Changes?
Choosing an in-network dentist is usually the easiest way to keep costs low and predictable. Here's why that matters so much with PPO plans.
- In-network dentists agree to accept a negotiated fee, so you won't get surprise charges above that amount.
- Out-of-network dentists can bill you for the difference between their normal fee and what your insurance considers "allowed." This is sometimes called balance billing.
- Your insurance may pay a smaller percentage for out-of-network care, meaning more comes out of your pocket.
- Some plans calculate out-of-network benefits using a lower allowed amount, shrinking what gets covered even further.
Our team at Charming Smiles of Ocoee always recommends double-checking network status directly with your dentist's office, not just the insurance company's website. Networks change, and a location might be in-network while another office under the same name isn't. It only takes a quick phone call to confirm before your visit.
What Does PPO Dental Insurance Typically Cover?
Most PPO plans sort services into three general categories. Coverage usually shrinks as treatment becomes more involved.
- Preventive and diagnostic care: Cleanings, exams, and X-rays, often covered at or near 100%.
- Basic restorative treatment: Fillings, simple extractions, and similar work, often around 70–80% covered.
- Major services: crowns & bridges, dentures, and other big procedures, often around 50% covered.
Some plans also include partial coverage for dental implants, orthodontics, or oral surgery, but this varies enormously. Always ask about specific exclusions, waiting periods, frequency limits, and any missing-tooth clauses before starting treatment. A missing-tooth clause, for example, might exclude coverage for replacing a tooth that was already gone before your policy started.
Common Coverage Questions Patients Ask
Patients often wonder if their PPO plan covers specific treatments like root canals, veneers, or Invisalign. Root canals are usually categorized as major or sometimes basic restorative work, depending on the plan. Cosmetic procedures like veneers and teeth whitening are often not covered at all, since they're considered elective. Orthodontic treatment, including Invisalign, sometimes has a separate lifetime maximum instead of an annual one.
How to Get the Most Out of Your PPO Dental Plan
Making the most of your benefits doesn't require an insurance degree. Just follow these simple steps before big treatment days.
- Confirm your dentist is currently in-network for your specific plan and location.
- Ask your dental office to verify your eligibility, deductible, and remaining annual maximum before treatment.
- Request a predetermination or pre-treatment estimate for costly procedures, like crowns or implants.
- Ask about frequency limits, such as how many cleanings or X-rays are covered per year.
- Check for waiting periods if you're new to a plan, especially for major or orthodontic work.
- Schedule preventive visits early in the year to use benefits before they reset.
- Ask about any rollover feature that might let unused benefits carry forward.
A predetermination isn't a guarantee of payment, but it gives you a strong estimate before you commit to treatment. Our front desk team is always happy to help walk you through this process so there are no surprises.
Why a Family-Friendly Dental Office Makes Insurance Easier
Busy parents juggling appointments for kids and grandparents alike know that dealing with insurance shouldn't add more stress to an already full schedule. A dental office that understands PPO plans inside and out can save you time, money, and headaches.
At Charming Smiles of Ocoee, we work with many major PPO insurance providers, including MetLife, Delta Dental, Cigna, Aetna, United Healthcare, Guardian, Humana, and more. If you don't see your plan listed, give us a call and we will happily verify your benefits for you.
What If You Don't Have PPO Insurance?
Not everyone has dental insurance through work, and that's okay. We also offer an in-house dental savings plan designed to help patients get affordable preventive and restorative care without traditional insurance. We also provide flexible payment plans and financing options like CareCredit, Alphaeon Credit, and Cherry Financing, so cost never has to stand between you and a healthy smile.
Common Mistakes Patients Make with PPO Dental Insurance
Even smart, careful people trip up on a few common PPO pitfalls. Here's what to watch for.
- Assuming a dentist is in-network just because the insurance company's general network name matches.
- Forgetting that the annual maximum resets, so unused benefits (without a rollover feature) simply disappear.
- Skipping a pre-treatment estimate for pricier work like implants or bridges.
- Not asking about waiting periods before scheduling major treatment on a brand-new plan.
- Overlooking frequency limits, which can mean a second cleaning in the same six months isn't covered.
Avoiding these small mistakes can save you hundreds of dollars a year. Our insurance & financing options page also breaks down more ways to plan ahead financially.
When Emergencies Happen: PPO Coverage for Urgent Care
Dental emergencies don't wait for convenient timing. If you're dealing with sudden pain, a cracked tooth, or swelling, your PPO plan generally still applies, though coverage percentages depend on whether the treatment falls under basic or major categories. Many plans cover emergency exams similarly to routine exams, but the actual treatment, like a root canal or extraction, may fall into a different cost-sharing tier.
Our emergency dentistry team moves quickly to get you comfortable and can help explain how your specific plan applies to urgent treatment. We know dental pain is stressful enough without insurance confusion piled on top.
Why Patients Trust Charming Smiles of Ocoee with Their PPO Benefits
Dr. Aliuska Lopez and her team have built a reputation in Ocoee for combining gentle, modern care with clear, honest conversations about cost. We take the time to walk through your specific plan details so you always know what to expect before treatment begins. Our general and cosmetic services are designed to fit real budgets and real insurance situations, not just ideal ones.
Curious what other patients say about their experience? You can visit us on Google — Charming Smiles of Ocoee to read honest reviews from families across Ocoee. We're also active on the Charming Smiles Facebook page and Charming Smiles Instagram page, where we share smile transformations and helpful dental tips year-round.
A Note on Trustworthy Insurance Information
Insurance rules can change from year to year, so it's smart to rely on trusted sources. The National Association of Dental Plans publishes regular reports on enrollment trends and plan features, which is where much of the data in this article comes from. We recommend checking your plan's official Summary of Benefits and Coverage for the most accurate, personal details.
Ready to Make Your PPO Benefits Work Harder for You?
Understanding your dental PPO insurance doesn't have to feel like homework. With the right team by your side, you can walk into every appointment knowing roughly what to expect, both for your smile and your wallet. Our staff at Charming Smiles of Ocoee is here to verify your benefits, explain your options, and make sure you get every bit of value from your plan.
Ready to schedule a visit or ask questions about your specific PPO coverage? You can book online anytime, or feel free to call us at (407) 378-3704 and our friendly front desk team will help sort out the details. We're conveniently located near Publix in Ocoee, and we can't wait to help you smile with confidence.
FAQs
Q: What is PPO dental insurance and how does it work?
A: PPO dental insurance lets you see almost any dentist, but you'll usually pay less by choosing one in your network. Your plan combines a deductible, coinsurance, and annual maximum to decide what's covered. It's the most common type of dental plan out there, so chances are good you already have one!
Q: Does dental PPO insurance cover out-of-network dentists?
A: Yes, most PPO plans let you visit out-of-network dentists, but you'll likely pay more. Your insurance may cover a smaller percentage, and you could be billed for the difference between the dentist's fee and what insurance allows. Sticking with an in-network provider, like our team at Charming Smiles of Ocoee, usually keeps things simpler and more affordable.
Q: What is a dental predetermination or pre-treatment estimate?
A: A predetermination is basically a sneak peek at what your insurance will likely pay for a treatment before you commit to it. It's not a guaranteed payment, but it helps you plan your budget with confidence. We're always happy to request one for you before bigger procedures.
Q: Are there waiting periods for major dental work or orthodontics?
A: Many PPO plans do include waiting periods, especially for major services or orthodontic treatment like Invisalign. This means you might need to be enrolled for several months before certain benefits kick in. Checking your plan details early helps you avoid surprises down the road.
Q: How can I check whether my dentist accepts my PPO insurance?
A: The easiest way is to call the dental office directly and ask them to verify your specific plan, since network status can change and vary by location. Our friendly team at Charming Smiles of Ocoee verifies benefits for patients every day, so just give us a call and we'll take care of the details for you.