How to Finance Veneers Without Stressing Your Budget
Learn how veneers financing works, compare payment plans and credit options, and find the smartest way to afford your new smile in Ocoee, FL.
Key Takeaways
- Single porcelain veneers average $1,455 (range $1,020–$2,506), with a full set of 6-8 costing around $13,954; financing spreads this into manageable monthly payments instead of one large payment.
- Dental insurance rarely covers veneers for cosmetic purposes, and HSA/FSA funds typically cannot be used unless treatment is medically necessary; verify coverage before committing to financing.
- Deferred-interest healthcare credit cards can charge interest retroactively to the original purchase date if the promotional balance isn't paid in full by the deadline; always confirm the exact payoff date before applying.
- Compare total repayment cost across all financing options, not just monthly payments; a low monthly figure over many years often costs significantly more than a higher fixed-rate option.
- Request an itemized written estimate listing tooth count, veneer material, prep work, follow-up care, and lab fees to avoid hidden costs and compare financing options accurately.
- Lower your out-of-pocket cost by phasing treatment (treating visible teeth first), joining a dental savings plan for 25% off additional procedures, or looking for practice specials on cosmetic consultations.
You've pictured your new smile a hundred times. Maybe it's the chipped front tooth that makes you hide your grin in photos, or the stubborn stains that no whitening strip can fix. Then you hear the price, and your excitement hits a wall. Sound familiar? Take a deep breath, because you have more options than you might think.
The good news is that veneers financing is very common, and it can turn one big bill into smaller, manageable payments. Veneers are thin coverings bonded to the front of your teeth, and most people see them as elective cosmetic care. That means you will usually pay out of pocket, but that doesn't mean you have to pay all at once.
In this friendly guide, we'll walk through each step, from getting a clear estimate to comparing payment plans. Whether you're a busy parent, a cosmetic enthusiast, or someone who gets nervous at the dentist, you'll leave with a plan you feel good about.
Why Veneers Financing Matters
Veneers are an investment in your confidence. They can fix chips, gaps, stains, and uneven shapes in just a few visits. But quality work takes skill, time, and custom lab work, which is why the cost adds up.
According to a CareCredit cost guide updated in 2026, the U.S. average for a single porcelain veneer is about $1,455, with a reported range of $1,020 to $2,506. A set of six to eight veneers averages about $13,954. Your price can change based on the material, your location, your dentist, and your treatment needs.
That is a big number to pay in one day. Financing helps you move forward now while spreading the cost over time. If you're curious about local pricing, our guide on veneers cost in Ocoee, FL is a great place to start.
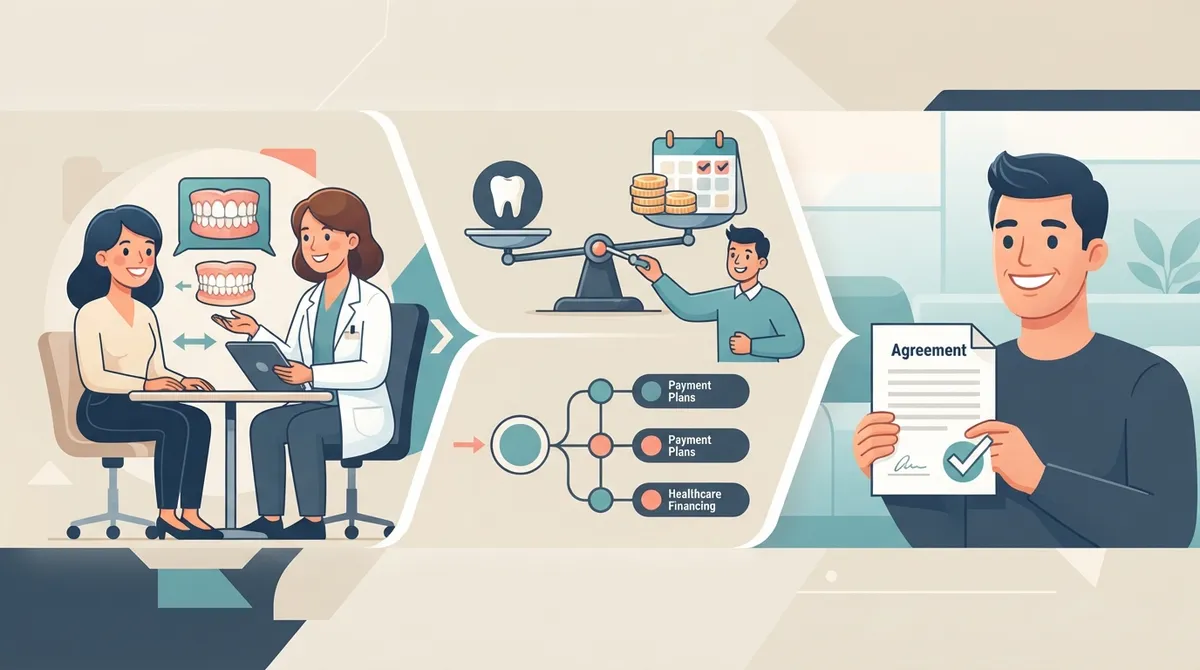
Step-by-Step: How to Finance Veneers
Here is a simple path you can follow. Take it one step at a time, and don't feel rushed.
- Book a consultation. Talk with a dentist about your goals and which teeth you want to treat.
- Ask for a written, itemized estimate. This is your roadmap for comparing options.
- Check your insurance and health accounts. Know what is and isn't covered before you plan.
- Explore payment options. Compare in-house plans, healthcare credit, and loans.
- Compare the total cost, not just the monthly payment. Look at interest, fees, and deadlines.
- Choose a plan that fits your real budget. Pick one you can keep up with comfortably.
Step 1: Start with a Consultation
A consultation lets you ask questions and see what's possible. At Charming Smiles of Ocoee, current specials include a free cosmetic consultation, so you can explore veneers, whitening, and more without pressure. Our spa-like office is designed to feel calm, which is a gentle welcome if dental visits make you nervous.
Step 2: Get an Itemized Estimate in Writing
Before you compare any financing, you need to know exactly what you're financing. A good estimate should list several things:
- How many teeth are included in the treatment
- The veneer material being used
- Any prep work or follow-up care needed
- Whether laboratory fees are part of the quoted price
This matters because a lower quote may leave out items that show up later. A clear estimate protects you from surprises. You can read more about the cosmetic options we offer on our Veneers page.
Will Insurance, HSA, or FSA Help?
This is one of the most common questions, so let's be upfront. Dental insurance usually excludes veneers when they are done only to improve appearance. If a veneer is recommended to treat a documented dental condition, coverage may differ, so it's smart to confirm benefits with your insurer before treatment.
HSA and FSA funds follow a similar rule. They generally can't be used for veneers done purely for looks. If your treatment is medically necessary, eligibility may be different. Check your plan rules and keep any supporting documents.
Even if veneers aren't covered, other parts of your care might be. Cleanings, exams, and restorative work often are. To learn what to ask your provider, see our post on dental insurance facts every patient should know. We also accept many major plans, including Delta Dental, Cigna, Aetna, MetLife, and more, for the care they do cover.
Your Main Financing Options Compared
There is no single best choice for everyone. The right option depends on your credit, your timeline, and how comfortable you are with monthly payments. Here is a quick comparison.
| Option | How It Works | Things to Watch |
|---|---|---|
| Pay upfront | You cover the full cost at once | Simple and no interest, but a big cash outlay |
| In-house payment plan | The dental office splits the cost into installments | Terms vary by practice, so ask for details in writing |
| Healthcare credit card | A card used for health and dental care, often with promotional periods | Deferred interest can be charged if not paid off in time |
| Personal loan | A fixed loan with set monthly payments | Rates and fees depend on your credit and lender |
Approval, rates, fees, and terms all vary by provider and lender, so always read the fine print before you sign.
In-House Payment Plans
Many patients love the simplicity of paying through the dental office. You can learn about ours on our payment plans page, or see the bigger picture on our insurance and financing options page. We also work with third-party partners such as CareCredit, Alphaeon Credit, and Cherry Financing, so you can choose what suits your budget.
Healthcare Credit and Deferred Interest
Healthcare credit cards often advertise promotional periods. For example, CareCredit describes deferred-interest periods of 6, 12, 18, or 24 months on qualifying purchases. Here is the catch: if you don't pay the promotional balance in full by the deadline, interest may be charged back to the original purchase date.
CareCredit also lists reduced-APR fixed-payment examples for qualifying purchases, such as 24 months at 17.90% APR, 36 months at 18.90%, 48 months at 19.90%, and 60 months at 20.90%. Offers and eligibility can change, so confirm the current terms before applying.
How to Compare Plans the Smart Way
It's easy to get drawn in by a low monthly number. But a small payment stretched over many years can cost more in the end. Here are the things worth checking.
- APR: The yearly interest rate you'll pay.
- Fees: Look for application, late, or origination fees.
- Promo deadline: Know the exact date any special offer ends.
- Minimum payments: These may not pay off the balance in time.
- Total repaid: Add it all up, not just the monthly amount.
Ask yourself one more question: could you still afford the payment if the promotional terms expired, or if your treatment plan changed? If the answer is yes, you're on solid ground.
Ways to Lower Your Out-of-Pocket Cost
Financing isn't the only way to ease the load. A few smart moves can bring your total down.
- Look for specials. Practices often run consultation deals or savings on cosmetic work.
- Join a dental savings plan. Our dental savings plan offers 25% off most other dental procedures, plus included exams, cleanings, and X-rays. It's a helpful option if you don't have insurance.
- Phase your treatment. Some patients treat the most visible teeth first, then add more later.
- Bundle your care. Combining services can sometimes simplify planning and payment.
Want to see how flexible plans can ease cost? Our article on how flexible financing makes dental care more affordable breaks it down further. And if you want a wider view of local options, check out dental payment options in Ocoee.
Are Veneers Right for You?
Before you finance anything, make sure veneers are the best fit. They are wonderful for chips, gaps, stains, and uneven teeth. But sometimes another treatment is a better match, such as whitening for surface stains or Invisalign for alignment. A skilled dentist will help you weigh the choices honestly.
Dr. Aliuska Lopez is known as a smile expert, and her gentle, personal approach helps patients feel heard. If you're also thinking about whitening, you can explore our teeth whitening services, or browse our full range of cosmetic dentistry. For a broader look at transforming your look, try our guide on how to transform your smile with cosmetic dentistry in 2026.
Take Care of Your Veneers After Financing
Once you've invested in your smile, you'll want it to last. Brush gently, floss daily, and keep up with your checkups. Our post on dental care for veneers in Ocoee shares simple habits that protect your results. Good care means your payments go toward a smile you'll enjoy for years.
While you're planning your self-care, remember that relaxation helps too. If you like to unwind, a service like Mobile Area Massage of Tampa Bay can be a lovely way to treat yourself after a big dental milestone.
Ready to Move Forward?
Financing doesn't have to be confusing or scary. Start with a clear estimate, check what your insurance and health accounts allow, compare your options side by side, and choose a plan that fits your real life. You deserve a smile you feel proud of, and you deserve a payment plan that doesn't keep you up at night.
Our friendly team in Ocoee is here to answer your questions and walk you through every option. You can book online in a few clicks, or follow along with smile transformations on the Charming Smiles Facebook page and the Charming Smiles Instagram page. You can also visit us on Google — Charming Smiles of Ocoee to read what our patients say.
Ready to take the first step toward the smile you've been dreaming about? Call us at (407) 378-3704 or find our location at 315 West Rd, Ocoee, FL 34761. We can't wait to meet you!
FAQs
Q: How much do dental veneers cost per tooth?
A: According to a CareCredit cost guide updated in 2026, a single porcelain veneer averages about $1,455 in the U.S., with a range of roughly $1,020 to $2,506. Your price depends on the material, your dentist, and your treatment needs, so a written estimate is the best way to know for sure.
Q: Can you finance dental veneers with monthly payments?
A: Yes, you can! Many patients use an in-house payment plan, a healthcare credit card, or a personal loan to spread the cost into monthly payments. Approval, rates, and terms vary, so compare the total amount you'll repay, not just the monthly number.
Q: Does dental insurance cover veneers?
A: Usually not, because veneers are most often considered cosmetic. If a veneer is recommended to treat a documented dental condition, coverage may be different, so check with your insurer before you start treatment.
Q: Can I use an HSA or FSA to pay for veneers?
A: Generally, HSA and FSA funds can't be used for veneers done only to improve appearance. Eligibility may differ if the treatment is medically necessary, so review your plan rules and keep any supporting documentation.
Q: How does deferred-interest financing work for dental care?
A: With deferred-interest offers, you get a promotional period such as 6, 12, 18, or 24 months. If you don't pay the full balance by the deadline, interest may be added going back to your purchase date, so always know your payoff date and read the agreement carefully.